Compare PEOs before your next renewal
We get quotes from the providers that fit your business and set them side by side with what you pay now.
- The provider you choose pays us, so there's no fee to you.
- A 20-minute phone call to start. Nothing to prepare.
- You reach Matt directly, before and after you sign.
Matt Mayers, Payroll & Benefits Consultant
Four steps, and you decide at the end
We talk for 20 minutes
You tell us how payroll, benefits and workers' comp work today and what you would change.
We request quotes
We ask the providers that fit your industry and size to quote.
You compare side by side
We put the options in one comparison next to what you pay today.
You decide
If you switch, we stay involved through setup and after. If you don't, you owe nothing.
Switching sounds like a lot of work. Here is what it involves.
Your time
A 20-minute call, then one person on your side who sends the new provider what's on its checklist.
Timing
Usually 30 to 60 days from the start to the first payroll. January 1 and the start of a quarter are the cleanest dates.
The setup
The new provider's onboarding team does it, and we stay on the calls until your first payroll runs.
Your current agreement
It sets the notice period, so we start a few months before your renewal.
Payroll, benefits, workers' comp and HR in one place
Payroll and tax filing
Every payroll run, federal and state tax filings, W-2s and direct deposit.
Employee benefits
Health, dental, vision and 401(k) options. Each provider's licensed benefits team explains its plans.
Workers' compensation
Often billed with each payroll instead of upfront. Each provider's licensed team explains coverage.
HR and compliance
HR advisors, employee handbooks, onboarding, and help keeping up with federal and Florida employment rules.
For Florida businesses with 5 to 500 employees, including restaurants and hotels, construction and trades, medical and professional offices, and retail.
Your current provider stays an option. If it's still the best fit, we'll say so.
Book a 20-minute callThe provider you choose pays us
That's how insurance brokers are paid too. Ask how we're paid on any option and we'll tell you. You can also ask any provider whether its price changes if you go to it directly.
Tipped staff raise questions providers answer differently
Who claims the FICA tip credit, how staff who work two jobs at two rates are paid, and how seasonal hours are tracked for the ACA. We ask each provider how it handles them and put the answers in your comparison.
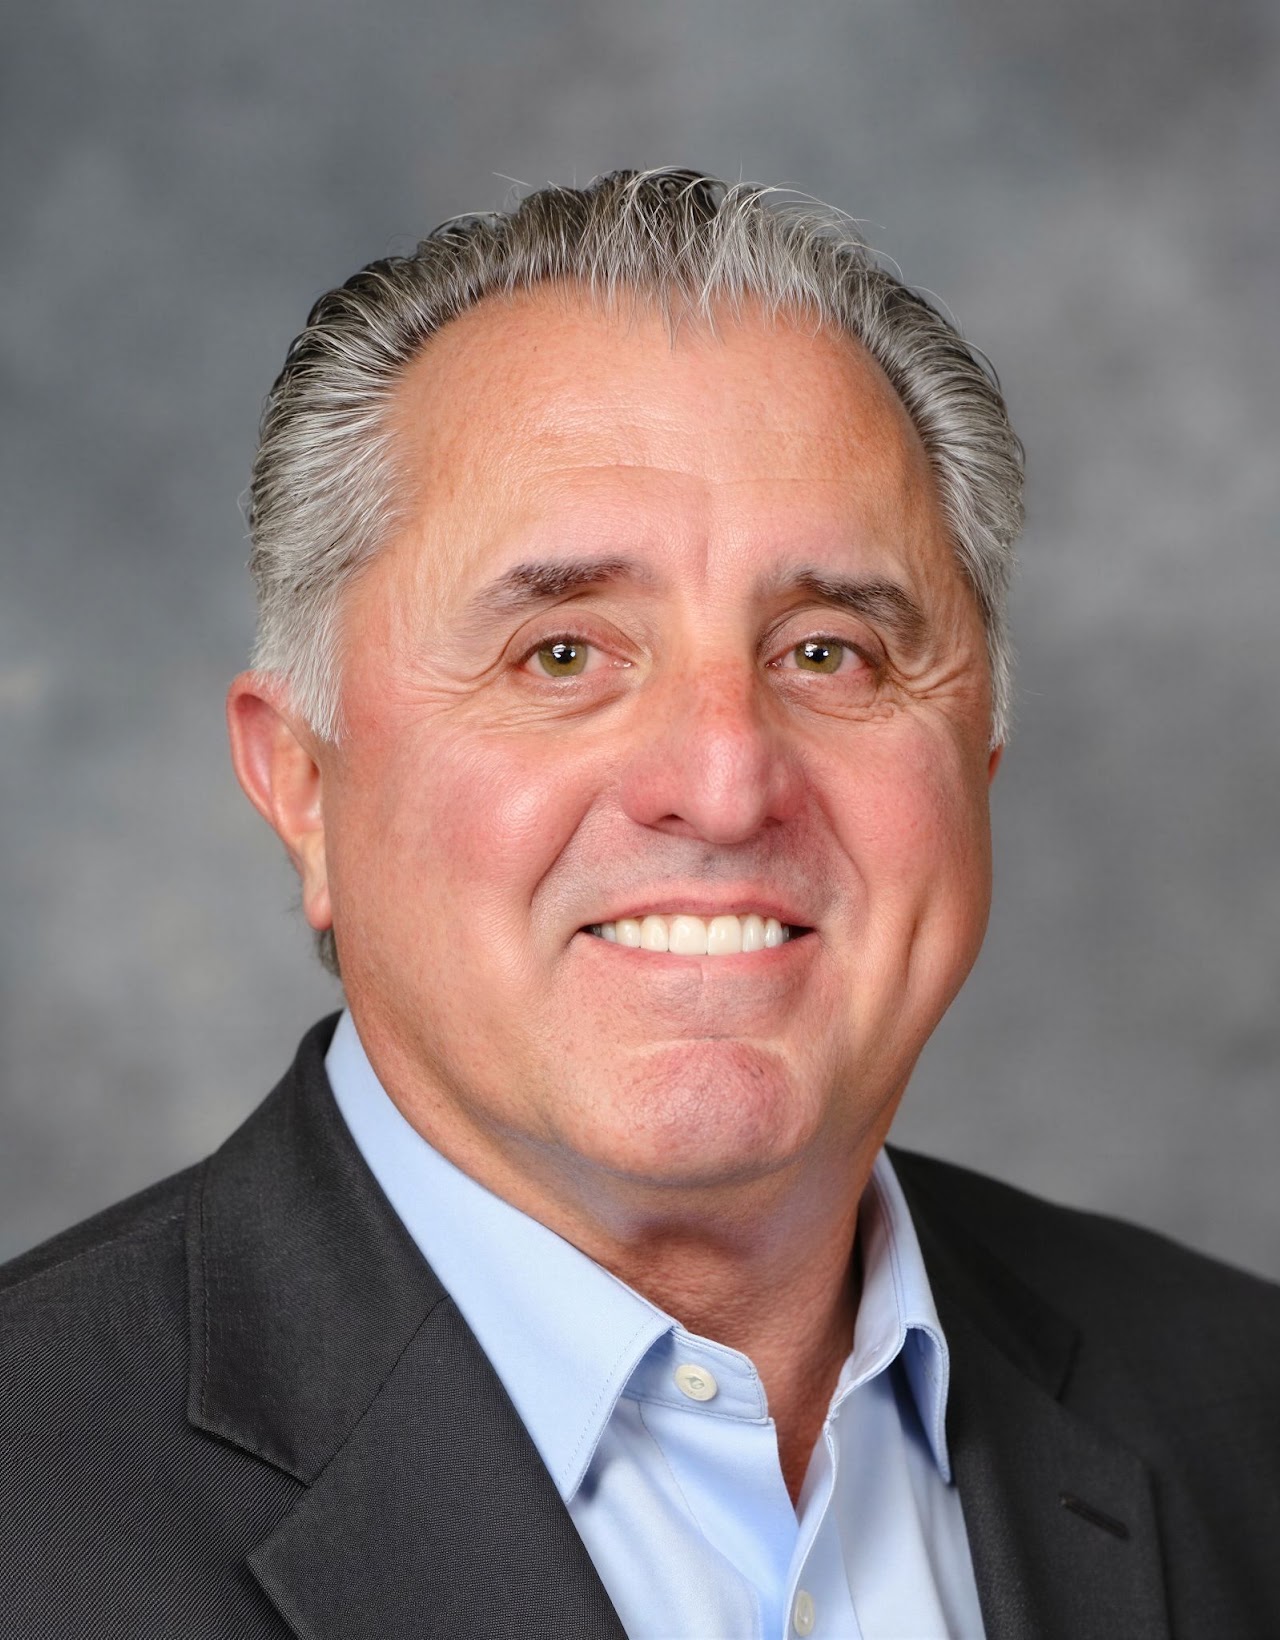
Matt Mayers
Matt is an independent PEO broker based in Safety Harbor. He makes the introductions and stays on the calls, and each provider's licensed team handles plan details.
Benefits are a large share of what you spend on people
Benefits' share of private employers' compensation costs, June 2026.
U.S. Department of Labor, Bureau of Labor Statistics, September 2026Average annual premium for employer family health coverage, 2025.
KFF Employer Health Benefits Survey, October 2025A study commissioned by NAPEO, the PEO industry association, found that businesses using a PEO grew more than twice as fast, had 12% lower employee turnover, and were 50% less likely to go out of business than similar businesses (January 2023 to January 2024).
NAPEO, September 2024What owners ask first
Does using a broker raise my price?
Ask us how we're paid on each option and we'll show you. You can also ask any provider whether its price changes if you go to it directly.
What is a PEO?
A professional employer organization (PEO) handles payroll, benefits, workers' comp and HR for many small and mid-size businesses at once. Your employees are co-employed: the PEO handles payroll taxes, benefits and workers' comp, and you keep running your business, including hiring, firing and the day-to-day work.
Why use a broker instead of going to a PEO directly?
Each PEO quotes only its own plans. We request quotes from the providers that fit your business and show them side by side, so you can see the differences in price and service before you choose.
What does your help cost?
Nothing. The provider you choose pays us.
Will I lose control of my business?
No. You decide who to hire, who to let go, what they're paid and how the work gets done.
I already use a PEO. Can you still help?
Yes. We'll compare your current setup with other options. Your current agreement sets the notice period, so it's best to start a few months before your renewal.
What will I need to provide?
For the first call, nothing. For quotes, providers usually ask for your headcount, recent payroll reports, your current benefits and your workers' comp history. We'll tell you exactly what each one needs.
Who answers my questions about health plans?
Plan details and pricing come from each provider's licensed benefits team. We set up that conversation and stay on it with you.
Does a PEO take over my tax liability?
The IRS says an IRS-certified PEO (a CPEO) is generally solely liable for paying the federal employment taxes on your worksite employees' wages. Not every PEO is certified, and we'll tell you which ones are. IRS: CPEO customers
Is my information confidential?
Yes. We share it only with the providers you agree to get quotes from. See the Privacy Policy.
See your options side by side
A 20-minute phone call. Nothing to prepare.
Prefer to write? Email Matt@MayersBenefits.com or use the form below.